NEWS CENTER
Steel inventories at key reporting enterprises fell in late October 2026, according to the China Iron and Steel Association (CISA). The figures offer steelmakers, traders and buyers a reference point for supply and procurement decisions, but the information provided does not identify a policy or rule change.
Inventories fell by 2.32 million tonnes
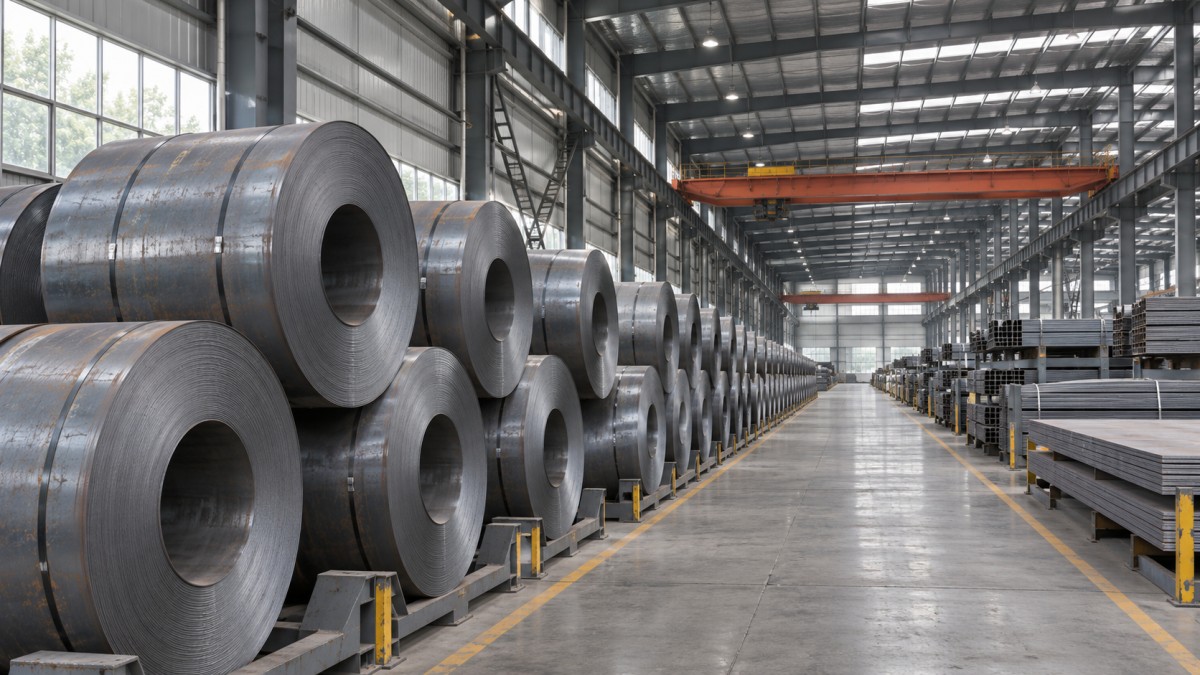
CISA data put steel inventories at key reporting steel enterprises at 14.90 million tonnes in late October 2026. That was 2.32 million tonnes, or 13.5%, lower than in the preceding ten-day period, but 760,000 tonnes higher than at the beginning of the year.
What the inventory figures may mean for supply decisions
Steel producers and distributors
Analysis suggests that the decline may prompt producers and distributors to review available stock against orders and planned deliveries. The aggregate figure alone does not establish availability for a particular product or supplier, so businesses may need to confirm those details before adjusting commitments.
Buyers and manufacturers
For steel buyers and manufacturers, a lower reported inventory may be relevant when comparing quotations and delivery schedules. It does not, by itself, confirm a shortage or a price change. Buyers could check product availability and lead times with suppliers when planning purchases.
Checks to make before changing procurement plans
Confirm product-level availability
Businesses may benefit from checking whether the materials they need are available from their suppliers. The reported total covers key enterprises and does not specify the inventory position of individual products or companies.
Review delivery commitments
Procurement and sales teams could compare existing order schedules with current supplier delivery estimates before making changes. Any revised timing would need to be confirmed with the parties concerned; the inventory figures do not establish a new delivery requirement.
Follow subsequent data and statements
Further association data and any relevant official statements may help businesses assess whether the decline continues. Companies should verify any later policy or rule announcements separately, since none is specified in the information provided for this article.
A market signal, not a new rule
From an industry perspective, the figures are best understood as an inventory signal rather than evidence of a policy being implemented or a regulatory requirement changing. The decline from the preceding period and the increase from the beginning of the year provide different comparisons; neither alone establishes the direction of future supply, demand or prices.
Use the figures alongside supplier information
The reported reduction provides a reference for assessing recent inventory movements, while leaving product-specific availability and subsequent market developments open to observation. A proportionate response is to monitor further data and verify procurement and delivery details directly, rather than treating the figures as a binding rule or a forecast.
Basis for this report and further verification
This article is based on the supplied news title, event timing and summary. The input does not provide a specific official source link; the figures and any subsequent updates should therefore be verified through relevant industry association information. Later inventory releases, official statements and industry feedback may also inform the assessment.